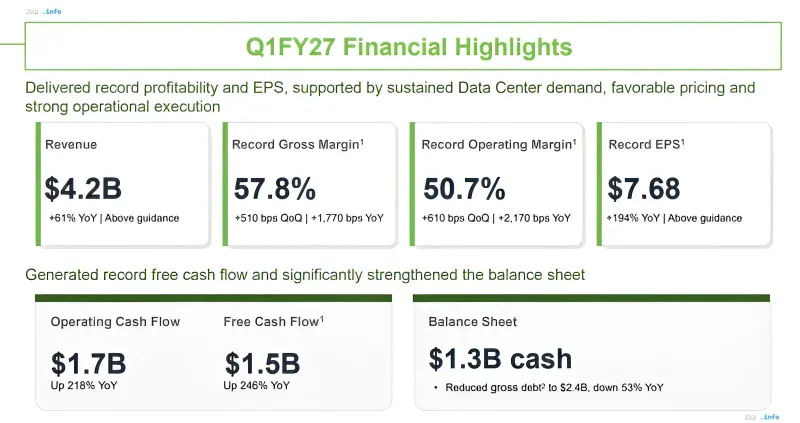
Seagate Technology, one of the world's largest hard drive manufacturers, has released its financial results for the first quarter of fiscal 2027, ended October 2, 2026. The company delivered record profitability and earnings per share, supported by sustained Data Center demand, favorable pricing, and strong operational execution. Seagate's revenue grew 61% year-over-year to $4.2 billion, exceeding management's previously guided range. EPS came in at $7.68, up 194% from the same period a year ago.
Data Centers as the Absolute Growth Driver
The Data Center and cloud platform segment remains the key driver determining Seagate's financial dynamics. Revenue in the data center segment surged 63% compared to the first quarter of the previous fiscal year, reaching $3.4 billion. This sector accounts for approximately 81% of the company's total sales in monetary terms. Seagate's cloud business has shown consistent positive momentum for 12 consecutive quarters, indicating structural rather than cyclical growth. Edge IoT revenue rose 52% year-over-year to approximately $784 million, or 19% of total sales.
Record Margins and Triple Profit Growth
Seagate's financial statements for the reporting period mark historic highs across all key margin metrics. Record Gross Margin reached 57.8%, up 510 basis points sequentially and 1,770 bps year-over-year. Operating Margin hit 50.7%, up 610 bps quarter-over-quarter and 2,170 bps year-over-year. The company's net income approximately tripled year-over-year, rising from about $549 million in Q1 FY26 to $1.76 billion in the reporting period. Earnings per share increased from $2.43 to $7.68.
Capacity Shipments: 220 Exabytes for the Quarter
In capacity terms, drive shipments for the reporting period reached 220 Exabytes, a 21% increase from 182 Exabytes a year ago. Nearline shipments, primarily targeting cloud and data center applications, grew 24% from 159 to 198 Exabytes. All other drives accounted for approximately 22 Exabytes, matching the previous year's level. The shipment structure confirms the dominance of high-capacity Nearline drives in the company's portfolio.
Cash Flow and Balance Sheet Strengthening
Beyond operational performance, Seagate generated record free cash flow and significantly strengthened its balance sheet. Operating Cash Flow stood at $1.7 billion, up 218% year-over-year. Free Cash Flow reached $1.5 billion, a 246% increase from a year ago. The company holds $1.3 billion in cash and cash equivalents, while total gross debt was reduced to $2.4 billion, down 53% year-over-year. This set of metrics indicates the company's transition to sustainable free cash generation while simultaneously lowering its debt burden.
Q2 FY27 Outlook
Seagate management provided guidance for the second quarter of the current fiscal year: expected revenue ranges from $4.7 to $4.9 billion, with earnings per share projected at $9.2 ± $0.2. The high end of the EPS guidance significantly exceeds even the record result of the first quarter, pointing to sustained high growth momentum and favorable pricing dynamics in the Nearline HDD market. Analysts tracking the report note that the combination of record margins, growing shipment volumes, and accelerating cash flow creates conditions for further upward revisions of the company's target market valuations.