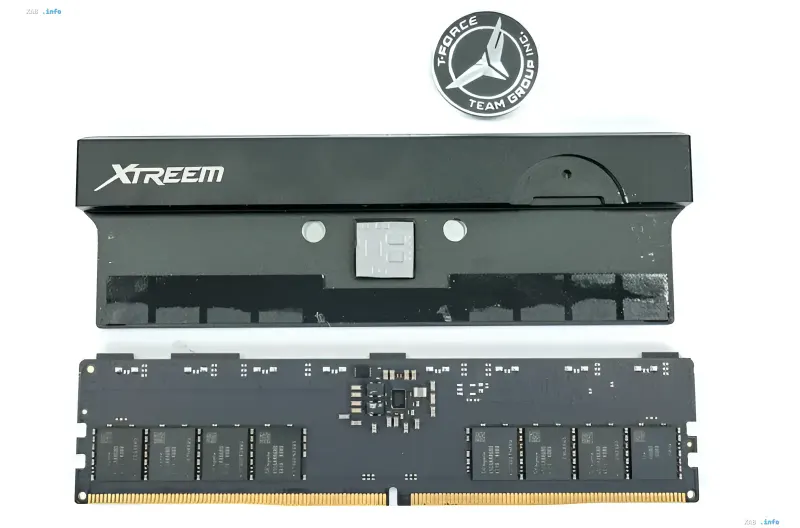
At its quarterly earnings conference held on November 1, 2026, representatives of the Taiwanese company TeamGroup delivered one of the industry's harshest forecasts in recent years: the most severe disruptions in memory supply chains are expected between the fourth quarter of 2026 and the second quarter of 2027. According to the company's estimates, this interval will mark the peak of the global shortage, and the current situation, where chips are still available at inflated prices, is merely the prelude to more acute disruptions.
Major Manufacturers Have Already Booked Capacity for 2027
The key driver behind the worsening shortage is that major memory manufacturers — SK hynix, Samsung, and Micron — have fully contracted their output for 2027 through long-term agreements with key clients. As a result, memory availability for other market participants is rapidly tightening. TeamGroup warns that a point may come when purchasing chips becomes impossible even with the necessary funds: while memory can still be bought today, albeit at a very high price, such an opportunity may soon vanish entirely.
Chinese Manufacturers Fail to Close the Gap
Even considering that Chinese companies CXMT and YMTC account for about 10% of memory market supplies, this volume is insufficient to meet demand. According to TeamGroup, supply-demand balance will not be achieved until the second half of 2028 at the earliest, and potentially even later. Thus, the industry is facing a horizon of at least two years of chronic shortage.
Sales Structure Shifts Toward AI Servers
Fundamental changes have also occurred in the company's revenue structure. Currently, the bulk of TeamGroup's sales come from the B2B segment at 64.6%, while direct consumer sales (B2C) account for only 35.4%. This contrasts sharply with the third quarter of 2025, when B2B share was 24.6% and B2C was 75.4%. Today, most revenue comes from companies developing servers for artificial intelligence systems rather than traditional consumer purchases, underscoring how memory demand has reorganized around AI infrastructure.
Prices Have Multiplied Over the Year
The scale of the price hike is clearly illustrated by contract price dynamics: in October 2025, the contract price for 16Gb DDR5 chips was $8.7, rising to approximately $48 by September 2026. In the spot market, where purchases occur outside long-term contracts, prices are even higher, carrying an additional markup of 30–50%.
Production Expansion and Financial Results
In the first quarter of 2027, TeamGroup plans to open a new manufacturing facility in New Taipei City, employing 1,000 people, with equipment installation scheduled for the same period. For the third quarter, the company's consolidated revenue reached NT$10.139 billion, equivalent to roughly $309.13 million USD. Together, these data points indicate that the memory industry is entering a phase where the shortage is becoming structural rather than temporary.