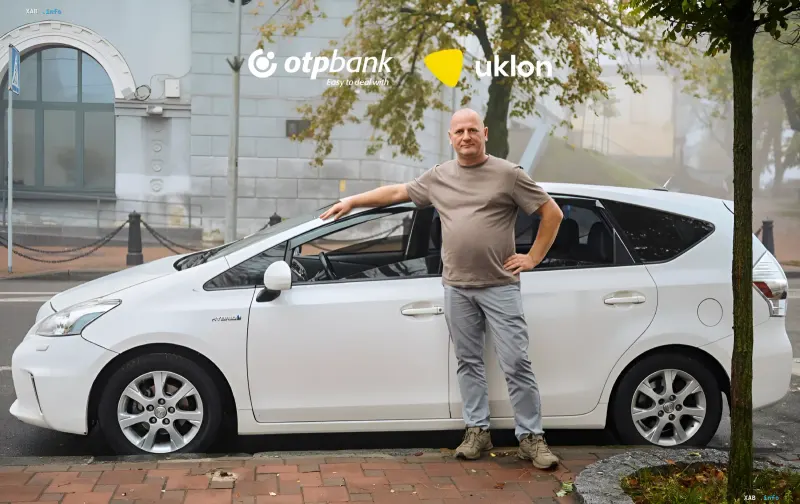
For ride-hailing drivers, a car is primarily a working tool whose condition directly affects income. When fuel and constant repairs eat up an increasing share of earnings, upgrading the vehicle becomes not a matter of comfort, but a way to maintain profitability. This is exactly the situation Mykhailo, an Uklon partner driver, found himself in: his Opel Astra regularly needed repairs, and fuel consumption reached 13 liters per 100 km. To avoid investing a significant portion of his income into an old car, he bought a 2012 Toyota Prius under the used car financing program from OTP BANK and Uklon. According to his calculations, fuel savings amount to about 20,000 hryvnias a month — an amount he estimates is enough to cover the monthly loan payment.
The path from Opel Zafira to a "fuel burden"
Mykhailo has been driving since 2008 and started fulfilling orders through ride-hailing services about three years ago. Now he works with Uklon, where, he says, he appreciates the ability to adjust order filters, choose trips, and contact support when necessary. Driving is an additional source of income for him: a few days a week he delivers goods around Kyiv, and in his free time he goes online. His first work car was an Opel Zafira, which he stopped using due to its age, after which he switched to an Opel Astra. Over time, this car also became a financial burden: fuel consumption reached up to 13 liters per 100 km, and frequent breakdowns reduced profits. "Something was constantly breaking down, and what I earned was essentially invested in repairs. I no longer felt any profit," the driver shares.
Loan instead of leasing: why registration in your own name matters
Mykhailo learned about the car financing program from OTP BANK and Uklon through notifications in the service app. When he started looking for a replacement for his Opel Astra in the spring, he contacted a bank representative he had previously cooperated with to discuss financing options for the purchase. He could not quickly save the full amount for a newer car: maintaining the vehicle took more and more money, and saving funds under such conditions was difficult. One of the key arguments was the opportunity to immediately register the purchased car in his own name — which, according to him, is how a loan differed from leasing, which he was also considering. "With a loan, the car is immediately mine. I pay gradually, and if any situation arises, I can sell the car and return the money to the bank. That makes more sense to me," the driver explains.
The mathematics of the decision: rental versus loan payment
Before buying, Mykhailo compared expenses. Renting a similar car would cost about 7,000–8,000 hryvnias a week, or about 30,000 a month. At the same time, the monthly loan payment was about 15,000 hryvnias. "Having done the math, I realized that if I take a car under this program, I will be paying about 15,000 hryvnias a month for my own car," he explains. According to the driver, OTP BANK requested income data from the relevant section of the Uklon app and then promptly determined the available financing amount. Then the driver independently found a car, checked it at a service station, agreed on the purchase with the bank, and after the purchase provided documents on registering the car in his own name. "The procedure is simple and clear, everything is resolved quickly. Getting money is not a problem if you have a good credit history and no negative experience with banks. The difficulty is rather in finding a normal car," he shares.
2012 Toyota Prius: savings that cover the loan
Mykhailo bought a 2012 Toyota Prius for $11,000. According to him, the car was in good condition and did not require repairs — it was only necessary to change the oil. The main advantage of the Prius was fuel savings: while he spent about 2,500 hryvnias per working day on the Opel Astra, he spent about 1,000–1,200 on the Prius. According to the driver's estimate, this allows him to save about 20,000 hryvnias a month. "I actually pay off the loan at the expense of fuel savings, and the earned money remains for my own needs. Every month I pay 15,000 hryvnias on the loan, while I save about 20,000 on fuel," he says. Using the example of a single working day, he explains the economics: if the revenue is 8,000 hryvnias, then after subtracting the conditional Uklon commission, about 6,000 remains, and after subtracting fuel costs on the old car, the net income was noticeably lower than it is now.
What to consider before making such a decision
Mykhailo's story is an example of how, for a ride-hailing driver, upgrading a car can turn from a major expense into a tool for reducing costs. The key factors he pays attention to are real fuel consumption, frequency of repairs, the difference between renting and the loan payment, and the ability to immediately register the car in his own name. At the same time, the financing process itself, in his experience, depends on credit history and the bank's willingness to work with income data from the service app, while the main difficulty is finding a car in good condition. For drivers whose old car is turning into a "financial burden," such calculations help make a balanced decision about changing their working tool.